For seasonal UK businesses, surviving the winter isn’t about hope; it’s about building a fortress of segregated cash systems and using predictive data as an early-warning radar.
- Your paper profits are irrelevant if your 30-day liquidity ratio falls, signalling an imminent cash crisis.
- A rolling 13-week forecast isn’t just an accounting exercise—it’s your strategic map to predict and navigate future liquidity bottlenecks.
- Actively ring-fencing your working capital in a separate account is the only way to protect it from being spent on non-essential projects.
Recommendation: Stop treating cash flow as a reactive problem. Start today by setting up automated micro-savings and a liquidity ratio dashboard to transform financial panic into strategic control.
For every UK retail and hospitality owner, the feeling is all too familiar. The sun-drenched, profitable summer months feel like a distant memory by the time January’s cold reality bites. You made good money, but the bank account is dwindling at an alarming rate. You look at your profit and loss statement, and it shows a healthy profit for the year, yet you’re struggling to pay suppliers and meet payroll. This boom-and-bust cycle feels inevitable, a constant threat of insolvency looming over the quiet winter quarter. Many business advisors will offer generic advice like « save more » or « cut costs, » but these platitudes fail to address the systemic issue.
The problem isn’t a lack of effort; it’s the lack of a robust, defensive financial structure. What if the key to survival wasn’t simply earning more in the summer, but building an unshakeable cash fortress designed to withstand the winter siege? The true path to stability lies not in hoping for the best, but in implementing a disciplined system of cash segregation, predictive forecasting, and ruthless capital efficiency. It’s about transforming your relationship with money from a source of constant anxiety into a strategic asset you control.
This guide provides a blueprint for that fortress. We will move beyond theory and provide actionable strategies to build automated cash buffers, interpret critical liquidity ratios that act as your early-warning system, and implement protocols to protect your capital. It’s time to break the cycle and build a business that thrives year-round, not just for a season.
This article will guide you through the essential strategies for building financial resilience. You’ll find a clear path from foundational principles to advanced tactics, all designed for the specific challenges of the UK’s seasonal market.
Summary: A Strategic Guide to Winter-Proofing Your Business Cash Flow
- How to Build a 3-Month Cash Buffer Using Automated Micro-Savings Accounts?
- Why Paper Profits Mean Nothing if Your 30-Day Liquidity Ratio Drops Below 1?
- Optimising Inventory Turnover to Free Up £50,000 in Trapped Capital
- Revolving Credit Facilities vs Business Credit Cards: Which Sustains Emergency Liquidity?
- When to Freeze Discretionary Spending to Prevent a Late-Year Liquidity Crisis?
- How to Build a 13-Week Rolling Cash Forecast to Predict Exact Liquidity Bottlenecks?
- How to Ring-Fence Critical Working Capital so It Never Gets Spent on Discretionary Projects?
- Forecasting Daily Liquidity Positions to Survive Aggressive Seasonal Demand Spikes
How to Build a 3-Month Cash Buffer Using Automated Micro-Savings Accounts?
The foundation of any financial fortress is a dedicated cash buffer. For a seasonal business, aiming for a reserve that covers at least three months of essential operating expenses is not a luxury—it’s a critical survival mechanism. This buffer is your first line of defence against unexpected supplier price hikes, a sudden drop in footfall, or any of the other variables that can trigger a winter cash crisis. The key, however, is not simply « saving » when you remember to; it’s about building an automated, disciplined system that works for you in the background, especially during your peak earning months.
Modern UK challenger banks like Starling Bank or Monzo Business are perfectly designed for this. Their « pots » or « spaces » features allow you to segregate funds for specific purposes without the administrative headache of opening multiple traditional bank accounts. By setting up automated rules, you remove willpower from the equation. A small percentage of every large payment received during the summer can be automatically swept into your ‘Winter Buffer’ pot, building your reserves incrementally and painlessly.
This strategy of systematic segregation is powerful. You should create separate, clearly labelled pots for your most significant liabilities. The most common and effective structure includes:
- VAT Pot: Automatically set aside 20% of your revenue here. When the VAT bill is due, the money is already isolated and ready, preventing the shock of a large, unplanned cash outflow.
- Corporation Tax Pot: A pot where you allocate funds based on your projected profits (currently 19% in the UK).
- Winter Buffer Pot: This is your core emergency fund. A dedicated percentage (e.g., 10%) of all income should be directed here until you reach your three-month target.
By automating this process, you treat saving as a non-negotiable business expense, just like rent or payroll. This discipline during the profitable season is what ensures you have the liquidity to navigate the lean months with confidence, rather than desperation.
Why Paper Profits Mean Nothing if Your 30-Day Liquidity Ratio Drops Below 1?
One of the most dangerous illusions for a business owner is staring at a profit and loss (P&L) statement that shows a healthy profit while the bank account is empty. Profit is an accounting opinion; cash is a fact. This is where understanding your liquidity ratio becomes your most important ‘liquidity radar’. Specifically, the 30-day liquidity ratio (also known as the quick ratio or acid-test ratio) tells you if you have enough easily accessible cash to cover all your short-term liabilities without having to sell any stock. A ratio below 1 is a critical warning sign that you are on the brink of a crisis.
The formula is simple: (Current Assets – Inventory) / Current Liabilities. A result of 1.5 or higher indicates a stable position. A result between 1.0 and 1.5 is an amber warning, signalling the need for caution. Anything below 1.0 is a ‘Code Red’ alert. It means that if all your bills came due tomorrow, you could not pay them without a fire sale of your inventory, which is the very engine of your revenue. This metric is far more valuable for day-to-day survival than your annual profit margin.
This visual representation helps to understand the urgency. An empty vessel is a business unable to meet its obligations, regardless of past profits.
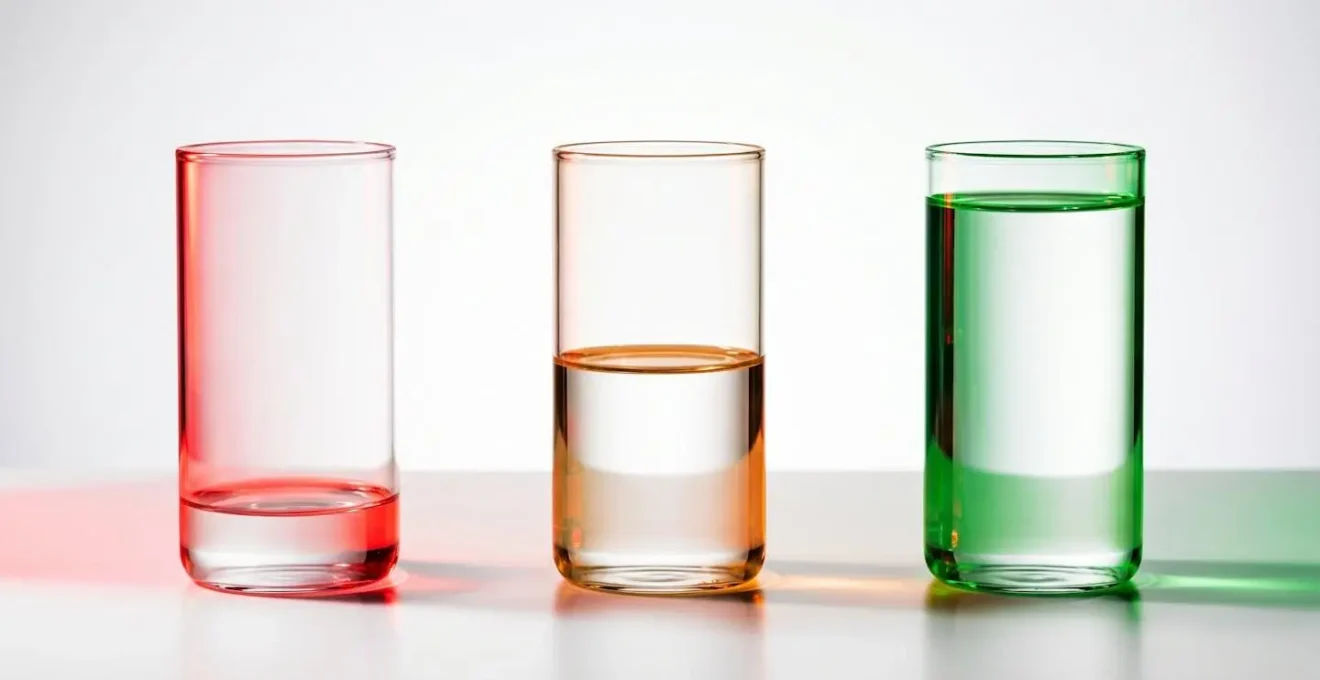
As this visual metaphor shows, monitoring your liquidity isn’t just about numbers; it’s about knowing the health of your business’s lifeblood in real-time. This is why a simple dashboard tracking this ratio weekly is more valuable than a detailed annual report. It allows for proactive decisions, not reactive panic. A UK-based online retailer, for example, transformed its finances by monitoring this ratio, which led them to identify and clear out slow-moving products, freeing up vital working capital that was previously trapped on shelves. The following table, based on common financial health checks, provides a clear action plan.
This framework provides clear, non-negotiable actions based on real-time data, as detailed in an analysis of liquidity management strategies.
| Ratio Range | Status | Required Action | Risk Level |
|---|---|---|---|
| Below 1.0 | Code Red | Immediate spending freeze, emergency funding | Imminent crisis |
| 1.0 – 1.5 | Amber | Freeze discretionary spending, accelerate collections | Moderate risk |
| Above 1.5 | Green | Normal operations, build reserves | Stable |
Optimising Inventory Turnover to Free Up £50,000 in Trapped Capital
For many retail and hospitality businesses, a significant portion of their cash isn’t in the bank; it’s sitting on shelves or in storerooms as inventory. This is what’s known as ‘trapped capital’. Every product that doesn’t sell is effectively a pile of cash you can’t spend. Improving your inventory turnover rate—the speed at which you sell and replace your stock—is one of the most powerful ways to release this trapped capital and inject it directly back into your working capital.
The most effective method for this is the ABC inventory analysis. This technique is based on the Pareto Principle (the 80/20 rule) and involves categorising your stock to focus your efforts where they matter most. It’s a strategic approach to inventory management that stops you from treating every product equally.
- ‘A’ Items: These are the top 20% of your products that generate 80% of your revenue. These are your stars. You need to manage them tightly, review stock levels weekly, and never run out during peak season.
- ‘B’ Items: This is the middle tier, roughly 30% of your stock generating 15% of your value. They are important but not critical. Monthly monitoring and seasonal ordering adjustments are sufficient.
- ‘C’ Items: These are the bottom 50% of your items that only contribute around 5% of your revenue. This is where your capital is trapped. These items clog up your shelves and your balance sheet. The strategy here is ruthless liquidation. List them on platforms like eBay.co.uk, bundle them, or sell them through local auction houses to convert them back into cash as quickly as possible.
Furthermore, you can proactively reduce future trapped capital. For seasonal items, negotiate ‘sale or return’ terms with your UK suppliers. This means you can return any unsold stock at the end of the season, effectively eliminating your risk. For online sales, exploring dropshipping partnerships can remove the need to hold certain stock items at all, freeing up immense amounts of capital and warehouse space.
Revolving Credit Facilities vs Business Credit Cards: Which Sustains Emergency Liquidity?
Even with the best planning, seasonal businesses can face unexpected cash flow gaps. Having a pre-approved line of credit is an essential safety net. However, choosing the wrong tool can be a costly mistake. The two most common options for UK businesses are Revolving Credit Facilities (RCFs) and business credit cards, and they serve very different purposes in sustaining emergency liquidity.
A business credit card offers immediate access to funds and is incredibly convenient for small, urgent purchases. If a critical piece of equipment breaks, a credit card provides an instant solution. However, they typically come with high interest rates (often 14.9-22.4% APR) and relatively low credit limits (up to £50,000), making them unsuitable for covering major expenses like payroll or rent for an extended period.
A Revolving Credit Facility (RCF), on the other hand, is a more robust solution for significant liquidity needs. It acts like a large, flexible overdraft with pre-agreed limits (from £5,000 to £500,000 or more). You can draw down funds as needed, repay them, and then draw them down again. As experts from Swoop Funding UK note in their guide, this structure is ideal for managing the fluctuating cash flow of a seasonal business.
Most revolving credit facilities have significantly lower interest rates compared to business credit cards, though some facilities come with a card as part of the deal.
– Swoop Funding UK, Revolving Credit Facility Guide
The key is to set up an RCF during your profitable months when your accounts look strong and you are most attractive to lenders. Waiting until you are in a crisis will drastically reduce your chances of approval. While it may take a few days to set up and might have a non-utilisation fee, its lower interest rate and higher limit make it the superior tool for weathering a serious winter downturn.
The choice depends entirely on the scale and urgency of your need, as this comparative analysis from UK funding experts illustrates.
| Feature | Revolving Credit Facility | Business Credit Card | Best For |
|---|---|---|---|
| Interest Rate | Significantly lower | 14.9-22.4% APR | RCF for larger amounts |
| Access Speed | 24-48 hours | Immediate with card | Cards for instant needs |
| Credit Limit | £5,000-£500,000 | £1,000-£50,000 | RCF for major requirements |
| Non-utilisation Fee | Often charged | None | Cards if irregular use |
| Setup Time | 3-5 business days | Same day possible | Cards for urgent setup |
When to Freeze Discretionary Spending to Prevent a Late-Year Liquidity Crisis?
One of the hardest decisions for a business owner is when to hit the brakes on spending. A common mistake is waiting until the cash has already run out. A strategic freeze on discretionary spending—costs that are not essential for day-to-day operations—should be a pre-planned response activated by specific data triggers, not by panic. This is a crucial ‘lockdown protocol’ for your cash fortress.
Discretionary spending includes things like marketing campaigns, new furniture for the restaurant, attending a trade conference, or even a staff party. While often valuable, they are not vital for survival. The decision to freeze them should not be emotional. It must be based on the cold, hard data from your liquidity radar. By establishing clear triggers, you create a non-negotiable rulebook that forces action before the situation becomes critical.
This decision carries significant weight, as it directly impacts your team and your growth plans. It requires a calm, data-driven mindset, not a panicked reaction.
As the image suggests, this is a moment of deliberate action. The goal is to preserve your core operational capacity. A freeze isn’t a sign of failure; it’s a sign of a disciplined financial strategy in action. It protects your ability to cover essential costs like payroll and supplier invoices, which are the lifeblood of your business. The following checklist provides a clear set of triggers to help you make this decision objectively.
Your Action Plan: Discretionary Spending Freeze Trigger Checklist
- Cash Reserve Trigger: Cash reserves are projected to fall below 1.5 times the next month’s payroll at any point in your 13-week forecast.
- Negative Trend Trigger: The business experiences two consecutive months of a declining overall cash position, even if still positive.
- Receivables Trigger: The value of invoices aged over 60 days exceeds 30% of your total accounts receivable.
- Quick Ratio Trigger: Your quick ratio (acid-test ratio) drops below 1.2 for two consecutive weeks.
- Overdraft Trigger: Your business overdraft usage exceeds 75% of its total limit for more than seven consecutive days.
How to Build a 13-Week Rolling Cash Forecast to Predict Exact Liquidity Bottlenecks?
A static annual budget is useless for managing the volatile reality of a seasonal business. To truly get ahead of cash flow problems, you need a 13-week rolling cash forecast. This tool is your long-range liquidity radar, giving you a three-month forward view of every pound coming in and going out of your business. It is the single most effective tool for predicting and preventing a crisis.
The « rolling » aspect is what makes it so powerful. Unlike a static forecast created once a year, a rolling forecast is a living document. As a success story highlighted by the British Business Bank shows, successful UK businesses update their forecast every single Monday morning. They input the actual cash movements from the previous week, and then add a new ‘Week 13’ to the end of the forecast. This constant process ensures you always have a 90-day forward view, allowing you to spot your ‘Maximum Pressure Point’—the specific week where cash is tightest—well in advance.
Building it is a methodical process. Start by listing all your anticipated cash inflows for each of the next 13 weeks: daily sales, credit card settlements, and expected invoice payments. Then, and most critically, list all your cash outflows. This must be exhaustive, including regular payments like rent and salaries, as well as the major, lumpy payments specific to UK businesses.
Integrating these statutory payment deadlines is what makes your forecast a true reflection of reality. Your cash position can be dramatically affected by the timing of these large, non-negotiable outflows.
| Payment Type | Frequency | Due Date | Typical Amount |
|---|---|---|---|
| VAT Return | Quarterly | 1 month + 7 days after quarter end | 20% of taxable sales |
| Corporation Tax | Annual | 9 months after year end | 19% of profits |
| PAYE/NI | Monthly | 22nd of following month | Variable based on payroll |
| Business Rates | Monthly/Annual | 1st of month | Fixed annual amount |
How to Ring-Fence Critical Working Capital so It Never Gets Spent on Discretionary Projects?
You’ve worked hard to build your three-month cash buffer. Now you must protect it. The single biggest threat to a cash reserve is the temptation to « borrow » from it for a seemingly good opportunity: a discounted stock purchase, a small refurbishment, or a new marketing initiative. This is how a healthy buffer gets eroded, leaving the business vulnerable when the real crisis hits. The solution is to create a ‘financial firebreak’ by ring-fencing your critical working capital.
Ring-fencing is the physical and administrative separation of your emergency funds from your day-to-day operational account. It’s about making it intentionally difficult to access this money. If the funds are sitting in the same current account you use to pay suppliers, it’s far too easy to dip into them. The goal is to create friction and force a deliberate, conscious decision before this protected capital can be touched.
The most effective method is the Two-Bank Ring-Fence Strategy. This involves opening a separate business savings account, ideally at a completely different bank from your main operating account. This separation is both psychological and practical. It stops the money from appearing as part of your available balance and prevents accidental spending. The strategy is simple to implement but requires strict discipline.
- Open a Separate Account: Choose a high-interest business savings account at a different banking institution.
- Transfer the Buffer: Immediately transfer your target buffer (minimum of three months’ operating expenses) into this new account.
- Create Friction: Remove any ‘quick transfer’ or ‘sweep’ facilities linking this savings account to your main operating account.
- Implement Dual Authorisation: For limited companies, mandate that any withdrawal from this ring-fenced account requires the approval of two directors. This enforces accountability.
- Formalise the Policy: Create a formal board resolution or a written policy that documents the purpose of the ring-fenced fund and the strict protocols for its use. This solidifies its status as a last-resort emergency fund only.
This strategy turns your cash reserve from a vague intention into a tangible, protected asset—the most secure part of your financial fortress.
Key Takeaways
- Seasonal survival depends on building automated cash ‘pots’ for tax and a 3-month buffer, not just generic saving.
- Your 30-day liquidity ratio is your true health metric; a ratio below 1.0 is a ‘Code Red’ alert, regardless of your P&L profit.
- Implement a rolling 13-week cash forecast, updated weekly, to predict and neutralise liquidity bottlenecks before they happen.
Forecasting Daily Liquidity Positions to Survive Aggressive Seasonal Demand Spikes
While a 13-week forecast gives you a strategic, long-range view, survival during the winter often comes down to managing your cash position on a day-to-day basis. This is especially true when you factor in the UK’s payment settlement lags, which can create dangerous, unseen liquidity gaps. The money you ‘receive’ from a customer is not the same as the cash hitting your bank account, and this timing difference can be critical.
As an impact analysis for UK businesses highlights, revenue received on a busy Friday from card transactions may not actually be accessible in your bank until the following Monday or even Tuesday. This is because card processing can take anywhere from T+1 to T+3 days (the transaction day plus one to three business days). Similarly, a BACS payment from a corporate client takes three working days to clear. Even a « same-day » CHAPS payment has a cutoff time (often around 4:30 pm), after which it will not be processed until the next working day.
This creates a significant risk. You might have a record sales weekend and feel cash-rich, yet be unable to pay a supplier whose invoice is due on Monday morning. To counter this, your forecast must be broken down to a daily level for any high-pressure weeks identified in your 13-week outlook. You must map out not just when revenue is earned, but when the actual cash settlement is expected. This granular approach allows you to anticipate short-term deficits and manage them proactively, perhaps by using a business credit card for a small purchase to bridge a two-day gap, rather than being caught off guard.
Ignoring these micro-timings is how even profitable businesses fail. Mastering your daily liquidity position is the final layer of defence in your financial fortress, ensuring you can navigate not just the seasonal downturn, but the daily challenges of cash flow management.
To truly break the cycle of seasonal financial stress, the next logical step is to move from reading to doing. Begin by implementing the 13-week rolling cash forecast for your business to gain immediate clarity on your financial future.